TLDR: Three central banks and three political calendars now set the cost and timing of acquisitions across the United States, the euro area and Switzerland, and franc-funded, well-structured buyers hold the advantage into 2027.
Politics Moved the Price of Acquisition Money Between October and November
Between the first week of October and the first week of November 2026, the three corridors in which Neumarz works moved apart. The United States voted for a divided government, the euro area met inflation of 3.8% with a pause, and Switzerland kept the lowest policy rate of the three while its parliament worked through the new agreements with the European Union.
The deal market shows the same split. Global mergers and acquisitions (M&A) reached $3.9 trillion in the year to date, up 28%, while the number of deals fell 8% to its lowest level since 2020 and third-quarter value dropped 41% from the second quarter1. Capital is still flowing, and it flows to fewer, larger and better-funded transactions. This note condenses the Neumarz white paper The Political Price of Money, published in November 2026.
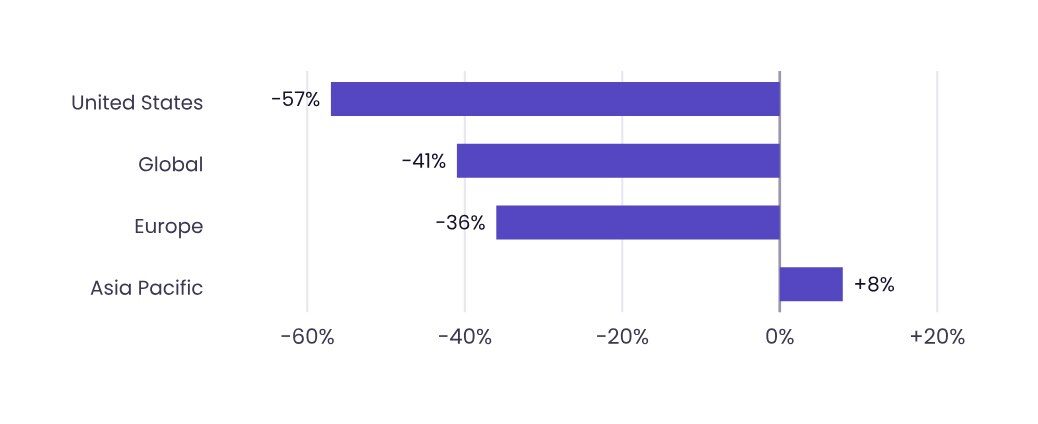
Year to date 2026: United States $2.0tn, an all-time high; Europe $882bn, a five-year high; Asia Pacific $613bn, a five-year high; Global $3.9tn, the highest since 2021, with deal count down 8%.
Three Central Banks Now Price Acquisition Debt at Three Very Different Levels
The Federal Open Market Committee kept the federal funds rate at 3.75% to 4.00% on 28 October by a 10 to 2 vote, with both dissenters voting for a further increase2. The European Central Bank (ECB) kept its deposit rate at 2.50% on 29 October and warned that energy prices “are likely to drive up inflation and lower growth”3. The Swiss National Bank (SNB) held its policy rate at 0%, with inflation at 0.8% in August4.
Politics added a second layer. Democrats won both chambers of the US Congress on 3 November, and Wells Fargo’s head of corporate and investment banking expects a “now or never” view to spur M&A before a stricter antitrust stance could return in 20285. In Europe, France’s 10-year borrowing cost rose above 5% on 21 October for the first time since 20026. In Bern, the Bilaterals III package with the EU moves to the National Council in the winter session7.
| Indicator | United States | Euro area | Switzerland |
|---|---|---|---|
| Policy rate | 3.75% to 4.00% | 2.50% | 0% |
| Next decision | 9 Dec | 17 Dec | 10 Dec |
| Political event | Democrats win Congress | French 10-year above 5% | Bilaterals III in parliament |
Exhibit 2. The three corridors in early November 2026. Sources: Federal Reserve; ECB via Banque de France; SNB; Brussels Signal; Le News.
Euro Acquisition Credit Repriced by More Than a Full Point Since August
The euro high-yield effective yield, the benchmark for most European sponsor-backed buyouts, rose from 5.46% on 14 August to 6.69% in early November, while its spread widened from 2.54% to 3.56%8. European mid-market direct lenders cut average leverage to 3.8 times earnings, from a peak of 4.3 times in 20249. At 3.8 times instead of 4.3 times, a buyer of a company earning EUR 10 million borrows about EUR 5 million less and funds that gap with equity, which shifts negotiating power towards buyers who fund from their own balance sheet or borrow in francs.
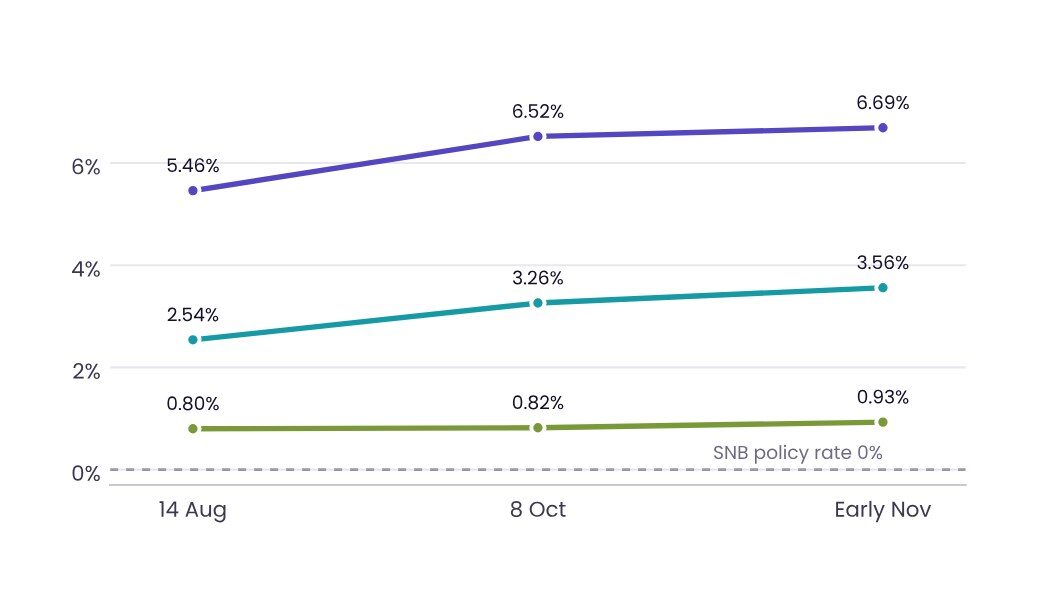
■ Euro high-yield effective yield ■ Euro high-yield spread ■ US investment-grade spread – – SNB policy rate, 0% throughout
Regulated Industries Earn Most Where Regulation Creates the Case for Scale
Europe’s largest banks are deploying surplus capital into domestic consolidation, and from January 2027 Article 21c of the EU’s sixth Capital Requirements Directive (CRD VI) requires non-EEA banks to serve EU clients through an EU branch10. Power networks drew some of the largest strategic cheques of the third quarter, including ENGIE’s $21 billion agreement for UK Power Networks1. Swiss pharmaceutical groups are investing behind the US tariff wall, led by Roche’s USD 50 billion and Novartis’s USD 23 billion programmes11, and the Swiss medtech owners who froze investment face buyers who price that pause into the offer, as Neumarz set out in its October study of Swiss medtech.
Growth Companies Raise in a Market That Rewards Structure
European venture funding reached $25 billion in the third quarter of 2026, up 77% on a year earlier, with 75% going to artificial intelligence (AI)12. Outside AI, liquidity runs through structure: secondary sales reached a record $220 billion in 202513, private credit lends to cash-generative companies at lower leverage, and corporates take minority positions with protective rights to access technology while avoiding a full integration.
Neumarz Positions Capital Into 2027 Around Four Convictions
- Swiss-funded acquisitions in the United States: positive. A 0% SNB rate against 3.75% to 4.00% at the Fed, inside a US regulatory window that bankers expect to close by 2028.
- European bank consolidation and power networks: positive. Surplus capital and regulated returns create the scale case.
- Sponsor-backed buyouts in the European mid-market: selective. Euro high-yield at 6.69% and leverage at 3.8 times call for structure before price.
- Partial liquidity through secondaries: positive. Owners realise part of their value while the company keeps growing.
The decisions that resolve most of the uncertainty sit on known dates: the Fed on 9 December, the SNB on 10 December, the ECB on 17 December, the EU deadline on US steel tariffs at the end of December and the CRD VI branch rule on 1 January 2027. Owners preparing a sale and acquirers building a US target list gain most by setting their funding, hedge and timetable before those decisions.
The full white paper sets out the exhibits, the ten-date decision calendar and the moves for owners, acquirers, boards, founders and family offices. Neumarz, a Kainjoo SA venture, makes it available to professional and qualified contacts as a free PDF download.
This article has been reviewed by Haider Alleg, Managing Partner at Neumarz, a Kainjoo SA venture.
This article is general commentary prepared for professional and qualified contacts. It is general information within the meaning of the Swiss Financial Services Act (FinSA), separate from any offer, solicitation, investment advice or personal recommendation, and advice on individual circumstances remains a matter for a dedicated mandate. Mandate-specific information is shared under a non-disclosure agreement (NDA) only.
References
- FinTech Global. “LSEG Data & Analytics: Mega-deal freeze puts record M&A year on the line,” 10 November 2026. https://fintech.global/2026/11/10/lseg-data-analytics-mega-deal-freeze-puts-record-ma-year-on-the-line/
- Board of Governors of the Federal Reserve System. “Federal Reserve issues FOMC statement,” 28 October 2026. https://www.federalreserve.gov/newsevents/pressreleases/monetary20261028a.htm
- European Central Bank, via Banque de France. “Monetary policy decisions,” 29 October 2026. https://www.banque-france.fr/system/files/2026-10/Monetary_policy_decisions_29-10.pdf
- Swiss National Bank. “Monetary policy assessment of September 2026: Summary of discussion,” 22 October 2026. https://www.snb.ch/en/publications/communication/summaries/zus_20261022
- Banking Dive. “Wells Fargo sees M&A urgency as Democrats gain ground,” 5 November 2026. https://www.bankingdive.com/news/wells-fargo-corporate-investment-banking-deals-2028/873881/
- Brussels Signal. “ECB holds rates despite inflation alarm as Lagarde prepares early exit,” October 2026. https://brusselssignal.eu/2026/10/ecb-holds-rates-despite-inflation-alarm-as-lagarde-prepares-early-exit/
- Le News. “Switzerland’s upper house puts its stamp on the EU deal,” 1 October 2026. https://lenews.ch/2026/10/01/switzerlands-upper-house-puts-its-stamp-on-the-eu-deal/
- Neumarz. “A Weaker Dollar Keeps US Buyers Out of Swiss SME Deals,” 4 November 2026 (ICE BofA indices via FRED). https://neumarz.com/us-buyers-swiss-sme-acquisitions-weaker-dollar-2026/
- Octus. “Data Drop: European mid-market margins edge up despite increasing lender competition.” https://octus.com/resources/blog/data-drop-european-mid-market-margins-edge-up-despite-increasing-lender-competition/
- GlobalCapital. “Rejuvenated European banking sector driven to still more M&A in 2026.” https://www.globalcapital.com/article/2fqcduueoptnxxhfmwnb5/rejuvenated-european-banking-sector-driven-to-still-more-m-a-in-2026
- Roche. “Roche to invest USD 50 billion in pharmaceuticals and diagnostics in the United States over the next five years,” 22 April 2025. https://www.roche.com/media/releases/med-cor-2025-04-22
- Crunchbase News. “Europe posted its strongest quarter in Q3 in 4 years,” October 2026. https://news.crunchbase.com/venture/q3-2026-europe-strong-quarter-ai-uk-germany-france/
- William Blair. “2026 Secondary Market Report.” https://www.williamblair.com/-/media/downloads/ib/2026/williamblair-pca-secondary-market-report-survey-2026.pdf